Certainly a growing and contentious policy debate on the role and purpose of autonomous robots in the “workplace”.
The potential of existential challenges to what we understand the “middle-class” to be [ in the context of a 20th Century definition of a “labour-force], coupled with genuine and profound advances in autonomous and now artificial intelligence, gives one a moment [at least] of pause. Certainly minds [ such as Musk, Hawking, Gates and Omohundro ] that closely consider these technologies and their implications would also agree. The existential challenges may extend far beyond the limited boundaries of what we call the “middle-class”.
As Prof. Stephen Hawking noted:
The real risk with AI isn’t malice but competence… a super intelligent AI will be extremely good at accomplishing its goals, and if those goals aren’t aligned with ours, we’re in trouble.
Consider the musings of Elon Musk and remember this phrase. Recursive self-improvement…:
Reforms and dislocations being witnessed in “modern” labour markets are perhaps the first symptoms of genuinely profound changes to what we understand work to be in the second half of this century. The implications of automation, “job-less growth” and widening skills and income inequality suggest profound changes in policy responses will be needed. Examples such as the development of “universal” or “basic income” schemes coupled with labour market and education reforms will no doubt begin to get more attention in the coming decade.
By 2018, around 1.3 million industrial robots will be entering service in factories around the world. In the high-revenue automotive sector, global investments in industrial robots increased by a record-breaking 43 percent (2013-2014) within one year.
Global Robotic Density = 66
[Source: IFR – Global Robotic Density]Contentious? Certainly. A recent study by the VDMA Robotics and Automation Association shows that previous waves of automation have not made labor obsolete in the German context. A case to “let it ride..”
[Source: Bloomberg]MIT Economist David Autor has some interesting things to say about similar changes. Simply put, Autor’s work suggest a bumpy ride, and the challenge is that:
human capital investment must be at the heart of any long-term strategy for producing skills that are complemented rather than substituted by technology……Significantly, mastery of “middle skill” mathematics, life sciences, and analytical reasoning is indispensable for success in this training.
Certainly the changes in economic and social policy are “well behind the curve” currently. I see little indication that this trend will improve. Given the latest work from the World Economic Forum’s research on The Future of Jobs where they state:
Today, we are on the cusp of a Fourth Industrial Revolution. Developments in genetics, artificial intelligence, robotics, nanotechnology, 3D printing and biotechnology, to
name just a few, are all building on and amplifying one another. This will lay the foundation for a revolution more comprehensive and all-encompassing than anything we have ever seen. Smart systems—homes, factories, farms, grids or cities—will help tackle problems ranging from supply chain management to climate change. The rise of the sharing economy will allow people to monetize everything from their empty house to their car.
Perhaps most saliently, they note:
While the impending change holds great promise, the patterns of consumption, production and employment created by it also pose major challenges requiring proactive adaptation by corporations, governments and individuals. Concurrent to the technological revolution are a set of broader socio-economic, geopolitical and demographic drivers of change, each interacting in multiple directions and intensifying one another. As entire industries adjust, most occupations are undergoing a fundamental transformation.
Proactive adaptation by corporations, governments and individuals. Historically, a challenge at the best of times. Anticipating and proactively adapting to what the WEF considers the fourth industrial revolution?
Good luck with that…
When considering the global policy responses to Climate Change, a phenomenon that we have decades of evidence-based, scientifically verified research to support our understanding of both the near and long-term implications for humanity [with unprecedented consensus ] and yet adaptation, let alone proactive adaptation seems non-existent in the policy sphere, beyond the well-intentioned.
WEF founder Klaus Schwab and board member Richard Samans opined that:
To prevent a worst-case scenario — technological change accompanied by talent shortages, mass unemployment and growing inequality — re-skilling and up-skilling of today’s workers will be critical…
Some great work from Amanda Cox at the New York Times looking at US Labour Markets:
At every age, the chances of not working have changed in the last 15 years. Teenagers are far more likely not to work. Older people are retiring later and working more. In the ages in between — the periods of life when most people work — the changes have been smaller, but they are still substantial.
Source: New York Times
In the late 1960s, almost all men between the ages of 25 and 54 went to work. Only about 5 out of every 100 did not have a job in any given week. By 2000, this figure had more than doubled, to 11 out of every 100 men. This year, it’s 16. (People in the military, prison and institutions are excluded from these figures.)
This from the Atlantic:
In 1974, the radio broadcaster Studs Terkel published a book of profiles to have “people talk about what they do all day and how they feel about what they do.” The title of the book was, simply, Working.
Source: The Atlantic
That was appropriate. Working was what people did all day, particularly if they were men in their 20s, 30s, 40s, or 50s. In the 1970s, as in previous decades, about 95 percent of men between the age of 25 and 54 were either working or actively looking for their next job. Only 5.5 percent of them were what economists consider “inactive”—out of the labor force.
But somebody revisiting Terkel’s project in the next decade would be encouraged to find a more flexible title. In each decade since the 1970s, the inactivity rate for 25-54-year-old men—the share of guys neither working nor actively seeking a job—has gone up. Each decade, not working becomes more and more a part of what we’re doing all day.
Can a 3D printer cool the Planet? Stay with me on this..
As we once againhear that the 1990 IPCC Climate modelling for the planet is “on trend” or “coming true”, I ponder the relationship between some of the major policy challenges Australia faces and see opportunity where at present we seem only to be experiencing confusion and much hand-wringing. It appears as clear as it was in 1990 that climate is the context for all other policy work.
There is no doubt that past and current political leaders have dropped the ball, and if my understanding of the research is correct, we have already locked in a temperature rise that current political leaders appear too timid or intellectually incapable of addressing.
We need greater strategic collaboration between education, IT, manufacturing, workforce and environmental portfolios than ever before. This is a challenge for all levels of government.
You might ask what the Climate, Australia’s NBN, Employment and Education policies have to do with one another? … Well, that’s my point.
There appears little or no effort [or perhaps ability] to truly connect some of the major policy challenges facing the country and the globe. Australia, as a nation, is very well placed to respond to and lead the changes required to address the challenges of global climate change and simultaneously address the current national and global debates about education and skills for modern communities and their economies.
There is [rightly] much concern in policy circles about the skills and opportunities that will be available to young people in the future. There is also, [rightly] concern about the relative level of skills and employability within the Australian workforce and the competitive advantage [or lack there-of] of the Nation over the coming decades.
If one looks at [for example] the current political debates surrounding teacher salaries and school performance, infrastructure spending for the National Broadband Network, the tense debates on Murray Darling Basin and particularly the ongoing critical debate about the necessary ”adjustments” or ”transformations” required in the Australian manufacturing industry, it would be easy to be overwhelmed by any one issue and you would certainly be excused for not relating one issue to the next, let alone, the debate about climate change.
I was struck by a piece from The Economist in 2011:
More than 20% of the output of 3D printers is now final products rather than prototypes, according to Terry Wohlers, who runs a research firm specialising in the field. He predicts that this will rise to 50% by 2020.
This got me thinking about the pending revolution in manufacturing and the preparedness [or not] of our Education and Industry sectors.
Concepts of school or home-based manufacturing seem fanciful, but for those of us that have witnessed the changes in the printing industry, it is not such a big leap to see what is coming.
Schools, universities and their IT departments were some of the earliest adopters of “new” dot-matrix and “desktop” printing technologies. We saw a profound change in an established “heavy” industry over just two decades, and we are still witnessing the fallout from those changes in the news and media fields today.
I have no doubt we will see a similar adoption and change in the coming decade, although this time, the change will be across the entire PROCESS of manufacturing.
Our educators, schools and universities are more important than ever before.
Consider the recent news.
In February of this year, an 83 year old woman had her lower jaw replaced, using a jaw that the surgeon PRINTED in a 3D printer.
As recently as last month, GE Aviation, part of the world’s biggest manufacturing group, bought a privately owned company called Morris Technologies. Morris Technologies is expert in 3D printing equipment and will be printing parts for jet engines. [The Economist]
A new start-up company, FormLabs, has even announced a high quality DESKTOP 3D printer in development.
It has been quite routine for about a decade for prototyping pieces in 3D printers. Architects, Engineers, Medical researchers, Physicists, Chemists and many others are all familiar with this field.
This is what 3D printing looks like:
Conceptually, 3D manufacturing becomes an additive more than subtractive process, thus less raw materials, [lower carbon footprint] and the benefit of unitization [less parts] is realised [because each item can be altered all within software, there is no re-tooling, or in many cases, any tooling [beyond the 3D printer and operator]. This fundamentally changes the nature of the enterprise, at every level, from supply, logistics, quality control, marketing… You name it, it changes.
The competitive advantage becomes almost solely the skill of the user; their ability to respond to market need and their ability to protect their intellectual property.
When one combines this with a highly trained and skilled workforce that has access to computing and bandwidth resources, you create the circumstances for genuine innovation.
Consider for a moment the major inputs required for an economy based on virtualised manufacturing.
The education, skills and collaborative abilities of the new manufacturers will be paramount. Their access to bandwidth will be central to their viability. Their relationships with research institutions will be critical. These manufacturers will not require some/many of the industrial-age inputs that have produced such carbon-intensive enterprises that now threaten the planet. This is one of the few times when the use of the word “revolution” could be genuinely justified and not considered hyperbole.
Innovation clusters and the ability to network strategically will be the norm.
In last months Technology Spectator, Thomas Birtchnell and John Urry envisioned four ways that 3D printing could change the world. They posited four alternate futures:
Home Factories – Where everyone has a 3D Printer.. They print all the “STUFF” they want. They buy designs online, trade in designs, even make their own designs. “Shops” with “stuff” disappear. Amazon has nothing to deliver.. This might seem fanciful, however, we all know how ridiculous a printer in every home seemed in 1981?? I knew lots of people that worked in typing pools?
Print Shops – Manufacturing “returns” to places such as the UK, USA or Australia. Efficiency gains and new business models create a renaissance. Again, this might seem impossible, given the “religion of the outsourced”, but consider an announcement from Time Cook, CEO of Apple this week..
Fab labs – Communities of interest, clusters of innovation, local or regional manufacturing hubs, hinged on open-source technology and skills. The high-tech “farmers markets” of the next decade.
A 3D Bubble – The 3D industry collapses, and remains a niche, specialist endeavour with little or no take-up. [Given integration of policy by governments, this might be more likely than not??]
I would suggest that any combination of the first three “futures” suggested by Birtchnell and Urry are desirable.
Australia seems particularly well placed to take advantage of the benefits in such changes to the manufacturing process if it is able to harmonise its key strategic public policy platforms in education, IT infrastructure, manufacturing and climate.
I think a 3D printer in a classroom just might cool the the planet!
A recent tweet from the NTEU ACT Division (@NTEUACT)
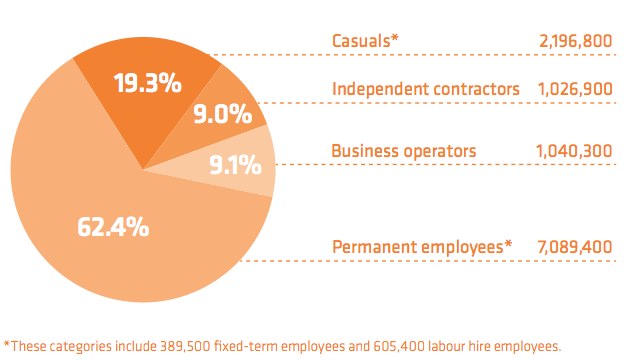
Australia has 2nd highest level of insecure work in OECD – after Spain.
We know that we are approaching 40% of the workforce undertaking insecure work.
Forms of Employment – Australia 2011
*Source: Lives on Hold – Unlocking the potential of Australia’s workforce.
We also hear much about “skills shortages” and the need for “flexibility”, yet the “elephant-in-the-room” when it comes to REAL skills shortages is the glaring lack of wage INCREASES – if skills were not present, wages would [should] go up… but more on that later.
Leigh Hubbard also has a worthwhile article in the latest Australian Nursing Journal making the point that this issue extends well beyond the “blue collar” phenomenon and extends to schools, universities and health professionals.
This is a critical economic and social policy issue for modern economies and something that touches all levels of Australian society. Increasing stressors within modern families and the wider community should not be underestimated. We have seen the historical tensions and results of disengagement and lack of opportunity in places like Hackney in the UK, and many who live and work in suburban and rural and regional Australia will also understand the social and economic pressures of day to day life. Even something as simple as a bus-ride can suggest underlying tensions in communities that are sadly, too familiar.
We are now in a position where, more than ever before, risk [in its broadest sense] is being outsourced at EVERY point of the life cycle; schooling, education, training, health, employment housing, manufacturing. All of these endeavours are changed by the rapid and transitory flow of capital investment. Stakes are so high, the risk and rewards so great, that the ability of many “traditional” enterprises to “invest” has altered markedly.
Investment now appears transitory, patterns looking much more like speculation than investment. Within the space of one generation or less, we now see returns needed on schedules of less than a decade, sometimes less than five years, when less than a generation ago, “investments” were considered inter-generational and conversely the skills and employment opportunities grew from this base.
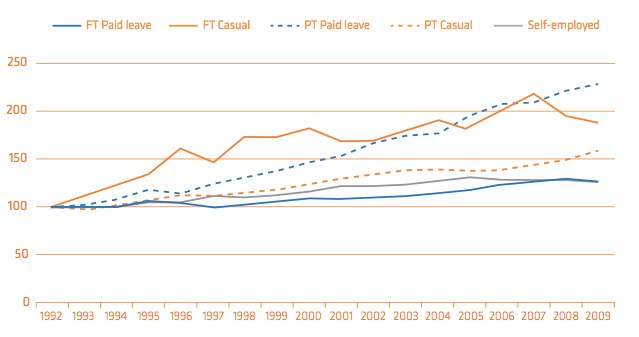
Non Standard Employment Growth in Australia 1992-2009
*Source: Lives on Hold – Unlocking the potential of Australia’s workforce.
This is no longer the case and the implications for education and training and the preparation of young people for modern labour markets has NEVER been more important. Now is the time to improve the conditions, quality and scope of our education sectors, if for no other reason, so investment in our social contract does not wane…
Research:
Lives On Hold – Independent Inquiry in to Insecure Work [PDF]
This NCVER report is about employers and how they value and use qualifications in their business decisions.
The research indicates clear differences in the value placed on and use made of qualifications by employers for different groups of workers and occupations. Qualifications are considered more important for higher-level occupations and employers use them predominantly to recruit new employees and to ensure regulatory compliance.